What the U.S. Fed hiking rates means for the loonie and for borrowers
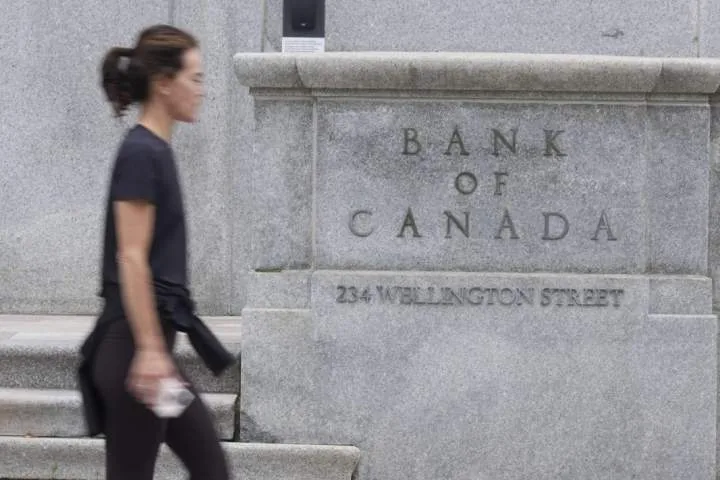
The U.S. Federal Reserve hiked interest rates for the first time in three years on Wednesday , and several economists say this could add pressure on the Bank of Canada to raise borrowing costs for Canadians sooner than later.
Canadian borrowing rates aren’t directly tied to changes made by the U.S. Fed, but there are some ripple effects, including changes to the loonie, which could influence future changes.
Derek Holt, economist and vice president at the Bank of Nova Scotia, said in a statement on Wednesday that he would be surprised if the U.S. rate hike doesn’t “add one more ingredient to pave the way” for Bank of Canada Governor Tiff Macklem to begin hiking soon.
Central banks, like the Fed and the Bank of Canada, aim to maintain the balance of their economies by ensuring inflation stays within a sustainable range (usually between one and three per cent), while also keeping borrowing rates low enough to allow the economy to grow.
The main way they strike that balance is by adjusting benchmark interest rates, and Canadians and businesses alike could wind up paying more to borrow money and take out mortgages and other loans if the Bank of Canada hikes its key rate.
Canada’s consumer inflation has been hovering around three per cent through July and August, while U.S. inflation was last reported at 3.4 per cent.
One of the main reasons the Bank of Canada could move to raise interest rates is if inflation gets too high, and a weaker Canadian dollar in the face of a stronger U.S. dollar can risk inflation rising in Canada. That’s because the currency diversion makes imported goods more expensive in Canada.
When the Fed’s rate announcement happened on Wednesday afternoon, the U.S. dollar increased in value, which sent the Canadian dollar’s equivalent value down by more than a quarter of a cent almost instantly.
Doug Porter, chief economist at the Bank of Montreal, says although that’s a relatively small drop, if the trend continues, then the Bank of Canada may lean more towards raising rates, like the Fed did.
“Were the Canadian dollar to soften a little bit more, it would put a bit of pressure on the Bank of Canada to possibly follow the Fed. But I don’t think we’re close to being there yet.”
The Fed’s new benchmark sits at minimum 3.75 per cent, while the Bank of Canada’s is 2.25 per cent. That divergence in key lending rates could also add pressure to the Canadian dollar because of the difference in borrowing costs, especially for businesses.
“They’re more than a percentage point and a half higher, so we’re starting off at much, much lower rates,” says Porter.
“Perhaps those really low interest rates in Canada are not sustainable for long if inflation stays at three per cent.”
But the Fed’s rate hike could affect Canadian borrowing costs even without a Bank of Canada rate hike, and that’s because of recent bond market jitters.
5News aggregated this summary from the outlet’s public feed. The full article, with all the context, is on globalnews.ca — the content belongs to Global News Canada.