Buying health insurance add-ons? Experts explain which riders are worth paying extra for and what to check
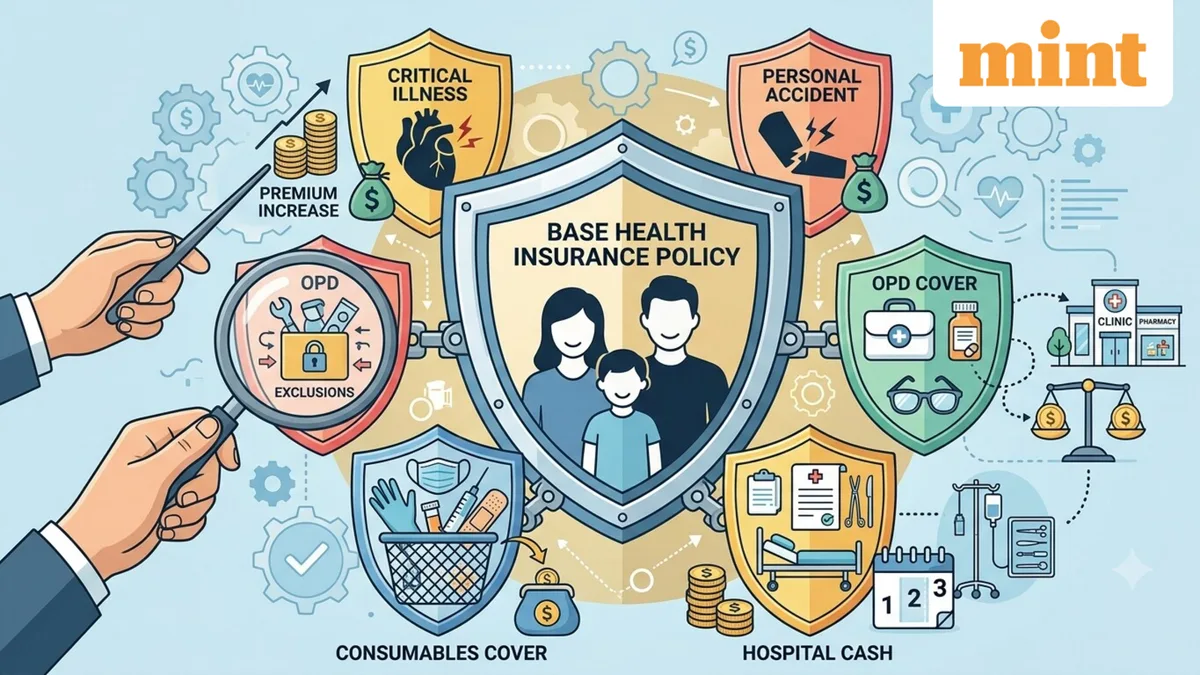
Health insurance is increasingly being sold with a menu of add-ons that promise extra protection, from consumables and hospital cash to OPD and critical illness benefits. But every additional feature comes at a cost, and choosing more riders does not necessarily mean better coverage.
For policyholders, the more important question is whether an add-on covers a cost that their base policy leaves them exposed to. Experts say consumers should first understand their existing coverage and then weigh the extra premium against the benefit, exclusions and conditions attached to each rider.
“There is no universal list of ‘must-have’ add-ons,” said Amitabh Jain, COO, Star Health Insurance. He said the choice should depend on factors such as age, family, health, lifestyle and future healthcare needs.
Consumables cover can help with expenses that may otherwise be excluded from the main health insurance policy. These can include items such as gloves, masks and syringes, depending on the terms of the policy.
Such expenses may seem small individually but can add to the amount a policyholder has to pay from their own pocket during hospitalisation.
Jain said consumables cover can reduce such out-of-pocket expenses, subject to policy terms. Consumers should therefore check exactly which items are covered rather than assuming that all hospital consumables will be included.
Hospital cash works differently from regular hospitalisation cover. Instead of reimbursing an actual medical expense, it generally pays a fixed amount for each eligible day of hospitalisation.
Jain said the benefit can help meet expenses such as caregiver costs, transportation, loss of income and other incidental expenses that may not be covered by the main health policy.
The value of this add-on should therefore be assessed against its additional premium , daily benefit and eligibility conditions.
OPD cover may be relevant for individuals or families that regularly incur outpatient expenses. Depending on the policy, it can provide benefits for consultations, treatments, dental and vision care and pharmacy expenses.
Renuka Kanvinde, Vice President – Health Insurance, TATA AIG General Insurance, said OPD coverage can provide such benefits, subject to the applicable policy terms and conditions.
Consumers should compare the additional premium with the policy's OPD limits and the expenses they expect to incur.
Critical illness or disease-specific benefits can provide an additional financial cushion when a policyholder is diagnosed with a specified illness. Personal accident cover, meanwhile, can provide financial support in case of accidental death or disability, Jain said.
However, these benefits are not necessarily relevant to every policyholder. Existing insurance cover should also be checked to avoid paying for protection that is already available elsewhere.
5News aggregated this summary from the outlet’s public feed. The full article, with all the context, is on www.livemint.com — the content belongs to LiveMint - Money.