Your FD and debt fund may face the same tax, here’s what should decide where you invest
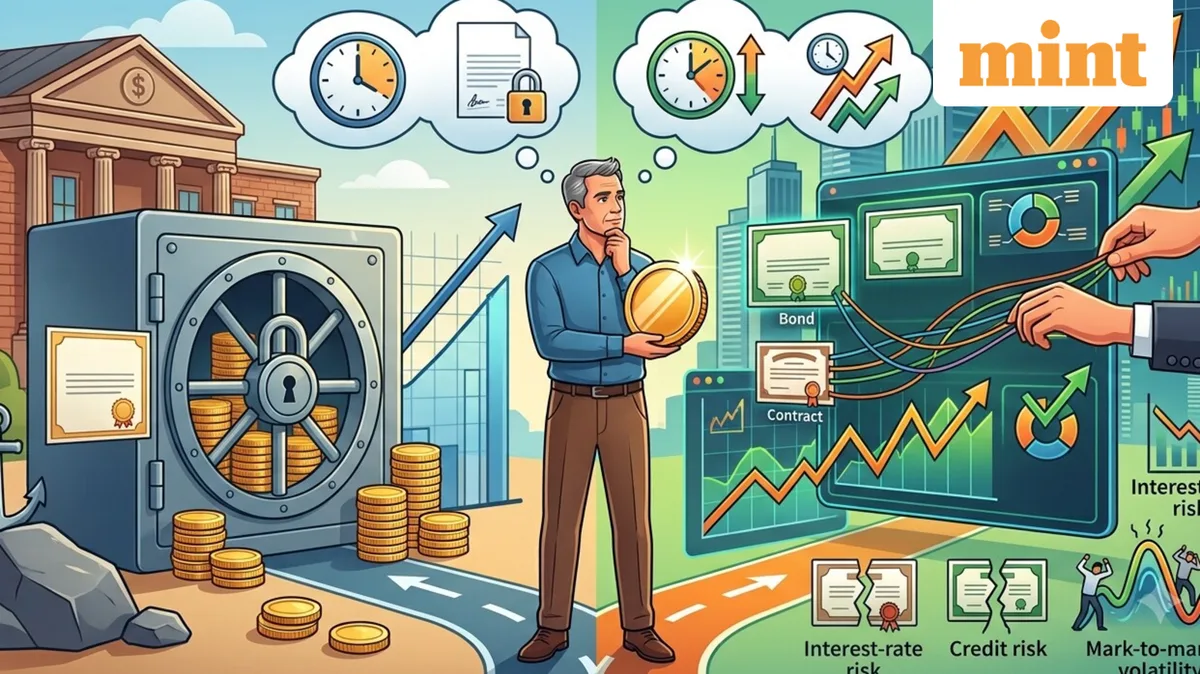
For investors choosing between bank fixed deposits (FDs) and debt mutual funds, taxation may no longer provide the clear advantage it once did. Both are generally taxed at the investor’s applicable slab rate. This means the decision now depends more on how much certainty an investor wants, how quickly the money may be needed and how comfortable they are with fluctuations in value.
The two products may both fall within the fixed-income bucket, but they work very differently. An FD offers a predetermined interest rate for a chosen tenure, while a debt fund’s returns depend on the bonds in its portfolio, interest-rate movements and credit conditions.
Rhishabh Garg, CEO, FundsIndia, said investors should not directly compare an FD interest rate with a debt fund’s historical return because the two numbers represent different things.
“An FD's rate is a contractual promise, fixed the day you book it, and it doesn't move regardless of what happens in the bond market afterward,” Garg said. A debt fund’s historical return, on the other hand, is backward-looking and reflects what happened to interest rates and credit spreads during that particular period.
A debt fund’s trailing one-year return can look unusually strong after a period of falling interest rates because bond prices generally rise when yields fall. Conversely, returns can look weak after interest rates have risen. Neither necessarily indicates what the fund will deliver during the investor’s next holding period.
For investors with a one-to-three-year horizon, the choice is less about tax efficiency and more about certainty versus flexibility, Garg said.
If the money is earmarked for a fixed and non-negotiable requirement within this period, the certainty offered by an FD may be more important than the possibility of a slightly higher return.
Investors who have some flexibility and are comfortable with fluctuations can consider short-duration or low-duration debt funds for this time frame, Garg said. Such funds can also offer easier partial withdrawals compared with breaking an FD prematurely.
“For someone in a higher tax bracket, arbitrage funds are also worth a look here,” he said. Arbitrage funds are taxed as equity rather than at the slab rate, although they carry their own risks and are not equivalent to FDs or debt funds.
Garg said the more appropriate comparison between an FD and a debt fund is the fund’s current portfolio yield-to-maturity (YTM) against the FD rate available today. Even this is only an approximation because the actual return from a debt fund will depend on how interest rates move and how the portfolio performs during the holding period.
The biggest difference between the two products becomes visible when markets move.
Garg identified three key risks for debt-fund investors. These are interest-rate risk, credit risk and mark-to-market volatility.
Interest-rate risk arises because bond prices generally move inversely to market interest rates. When rates rise, bond prices can fall, putting pressure on a debt fund’s NAV. The impact can be greater in longer-duration funds.
An FD, once booked, is not affected by subsequent movements in market interest rates.
5News aggregated this summary from the outlet’s public feed. The full article, with all the context, is on www.livemint.com — the content belongs to LiveMint - Money.