New UPI charges: what changes for your QR payments, SIPs and mutual fund investments
This is a Mint Premium article gifted to you. Subscribe to enjoy similar stories.
From 15 October, some transactions on the unified payments interface (UPI) will attract a merchant discount rate (MDR)–a fee a merchant pays to the payments ecosystem for processing a digital payment.
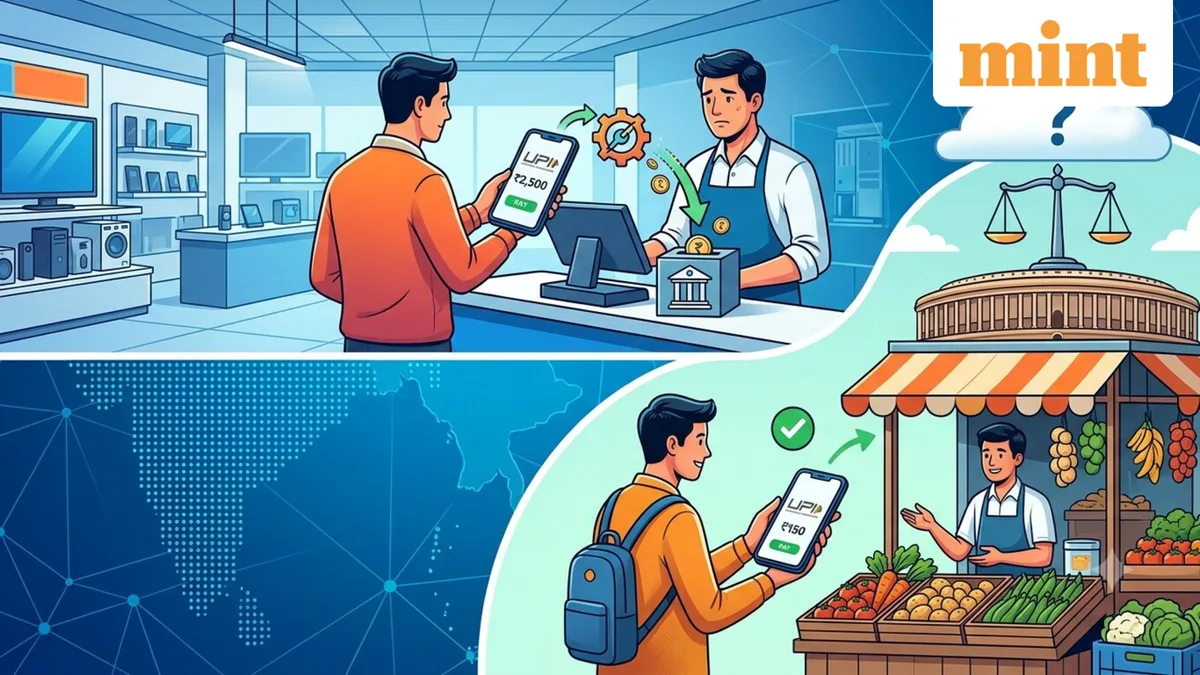
An MDR of 0.4% will apply to person-to-merchant (P2M) UPI transactions above ₹ 2,000, capped at ₹ 300. But you will not be charged any extra fee for using UPI . If your bill at a supermarket comes to ₹ 3,000, you scan the QR code and pay ₹ 3,000 as usual. The merchant, however, will pay an MDR of ₹ 12, or 0.4%, to its bank.
This is not a blanket cost with some categories attracting a lower fee. Railways, telecom, insurance, credit card bills and fuel will attract a flat MDR of ₹ 5 for transactions above ₹ 2,000. Capital-market transactions, including mutual funds, securities and brokers, will attract an MDR of 0.02%. These, too, are capped at ₹ 300.
Person-to-person (P2P) payments will not attract any fee and will continue to be free. So, when you transfer money to a friend, or pay your local vendor on their UPI app directly, the transaction will remain free as long as the payment is being made to an individual account and is classified as a P2P transaction.
Suppose you purchase groceries worth ₹ 5,000 at your local kirana store by scanning the shop's QR code. While you still pay ₹ 5,000, the store will incur an MDR of ₹ 20, or 0.4% of the transaction amount. This ₹ 20 is divided among the companies that enable the payment.
Under the framework, the kirana store will pay the full 0.4% to its acquiring bank—the bank that enables it to accept the UPI payments. From this pool, the acquiring bank gets 0.12%, the bank that issued the customer's account gets 0.16%, the customer's payment service provider gets 0.04% and the UPI app provider gets 0.08%.
The NPCI notification specifically says, “UPI App providers shall NOT charge Platform Fee or any other charge for any payment made through UPI. UPI applications are explicitly restricted from levying platform fees on UPI transactions.”
Industry stakeholders also believe merchants are unlikely to pass the MDR cost on to customers, given that they already absorb higher charges on other payment modes.
“A typical credit card MDR ranges between 1.5% to 2.5% while that of debit cards is around 0.9% per transaction. It is highly unlikely that merchants will pass the UPI MDR cost on to customers, as the rate remains very low,” said Reeju Datta, co-founder, Cashfree, a payment gateway. “Since most merchants already absorb higher MDRs on credit and debit cards, passing on the significantly lower UPI MDR is improbable,” Dutta added.
Rupay debit cards carry a zero MDR regardless of the transaction value and remain exempt even under the recently proposed framework.
However, over time, businesses could factor payment-processing costs into their overall pricing, just as they do with other operating expenses. But the MDR itself cannot be passed on as an additional UPI charge at checkout, as per a statement from the finance ministry.
5News aggregated this summary from the outlet’s public feed. The full article, with all the context, is on www.livemint.com — the content belongs to LiveMint - Money.