Why a ‘settled’ loan status can hurt your credit score; know the solution
If a borrower takes a loan and fails to repay the full amount, the lender may agree to close the loan once the settlement amount is paid. However, the way the account is reported to credit bureaus can continue to affect the borrower's ability to access credit in the future.
A “settled” status indicates that the lender accepted an amount lower than the original dues. This can make the borrower less favourable in the eyes of future lenders. Knowing the steps to take after a settlement can help improve your credit profile before applying for new credit card or another loan.
A loan is generally marked “settled” when the borrower and lender agree on an amount lower than the total outstanding dues and that agreed amount is paid. It is different from a “closed” account as it refers to full amount being paid, according to CIBIL's own explanation.
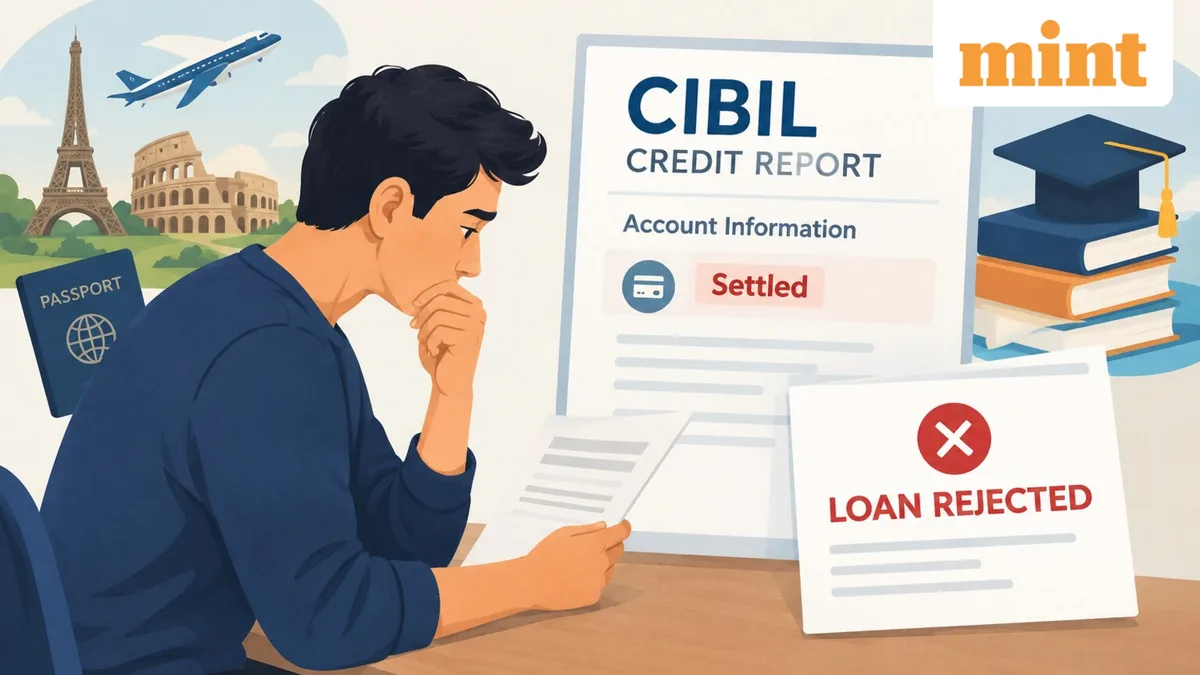
For example, let's say a person took a personal loan worth ₹ 5 lakh to fund their trip to Europe and they had been the monthly installments on time. But, after some time, the borrower had a medical emergency in their family and therefore couldn’t pay the remaining amount of ₹ 3 lakh.
As a result, the bank agrees to a certain settlement amount, which in this case, can be ₹ 1.5 lakh (for illustration purposes). Once that amount is paid, the borrower no longer has the agreed settlement amount outstanding.
However, it does not mean there won't be any more consequences and they can freely ask for credit later. The person's credit report can still show that the original obligation was not fully repaid.
Your past credit behavior has a long-lasting impact. Lenders view “settled” as risky, primarily because if you haven’t met your repayment obligation before, there are chances that you might do this again, according to CIBIL.
The individual who took a personal loan to fund their Europe trip and settled the outstanding amount because they could not clear it in full can think their immediate financial burden has been resolved, but the impact could come later.
Let's say, the same person later plans to pursue higher education . They compared the interest rates available on education loans and selected one to apply for but within a few hours, their loan application gets rejected after the lender found a “settled” status under the Account Information section of their CIBIL report.
Though the person might have thought that the “settled” status has a positive connotation, it wasn't the case.
5News aggregated this summary from the outlet’s public feed. The full article, with all the context, is on www.livemint.com — the content belongs to LiveMint - Money.