End of free era for UPI: Here's what changes, what doesn't
This is a Mint Premium article gifted to you. Subscribe to enjoy similar stories.
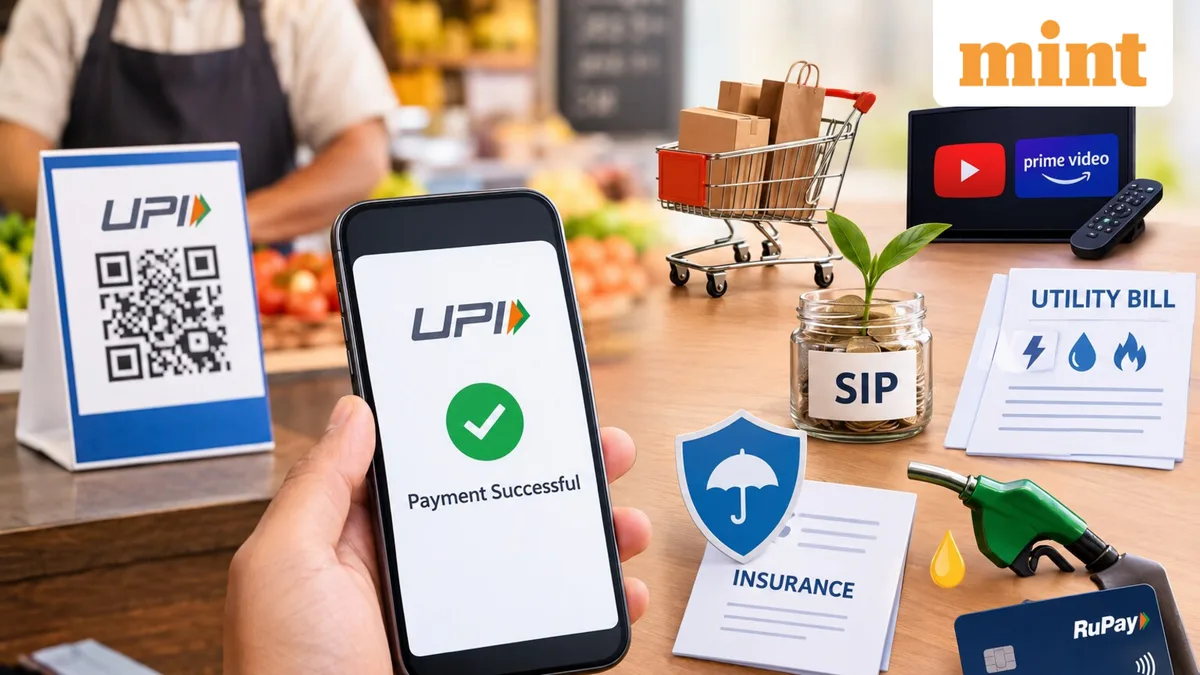
From 15 October, Unified Payments Interface (UPI) merchant transactions move from a zero-fee structure to a modest, tiered one, a narrow chang e with wider implications for how India's payments system sustains itself. The standard fee is 0.4%, applied to person-to-merchant payments above ₹ 2,000 and capped at ₹ 300 beyond ₹ 75,000. Railways, telecom, insurance, fuel, and a few other essential categories pay a flat ₹ 5 instead, while capital market transactions carry a lower 0.02%, also capped at ₹ 300. Consumers pay nothing, and transfers between individuals remain free as before. Small and micro merchants are already exempt. Vendors receiving up to ₹ 1 lakh a month through UPI QR codes stay at zero fee, and this covers more than 95% of all merchant transactions by volume. So, the new fee touches only a small, higher-value slice of commerce, not the everyday retail most Indians associate with UPI.
For most users, this change may not be noticeable in daily life. Everyday spending at local vendors, on transport, and on small retail purchases remains free, exactly as they were before this announcement. The rule is explicit that merchants cannot pass this fee to customers, and payment applications are barred from introducing platform charges of their own. The more interesting impact could be indirect. A revenue stream for the payments ecosystem could create more room for new products around UPI, including richer credit options, buy-now-pay-later products at merchant points, and merchant-funded rewards. At the same time, higher-value transactions, EMIs , large retail purchases, and sizeable business-to-consumer payments will carry a cost for merchants, even though they cannot recover it directly from customers. Whether this cost finds its way into pricing over time is a question worth watching, though the current framework does not permit merchants to recover it directly.
Government estimates, citing industry figures, put the cost of running UPI's infrastructure, its servers, fraud detection systems, and bank-side support, at close to ₹ 20,000 crore a year. Some of this has so far been covered through a government subsidy meant to be temporary, not permanent. A fee gives the payments industry its own revenue line, one that could eventually fund better fraud detection, faster settlement, and merchant tools that don't yet exist at scale. There is also a comparative point worth noting. Card networks globally already pair free or low-cost consumer access with a commercial layer on the merchant side, and several major payment systems abroad follow a similar pattern. Seen this way, the shift places UPI closer to a more established international structure rather than marking a significant departure for the system.
The fee also raises concerns that are difficult to dismiss. Though it is capped at 0.4%, it could introduce friction at a point when digital payment habits are still forming for a large number of smaller merchants across the country.
5News aggregated this summary from the outlet’s public feed. The full article, with all the context, is on www.livemint.com — the content belongs to LiveMint - Money.