₹10,000 SIP, ₹87 lakh corpus: Why staying invested for 20 years may be harder than the calculation suggests
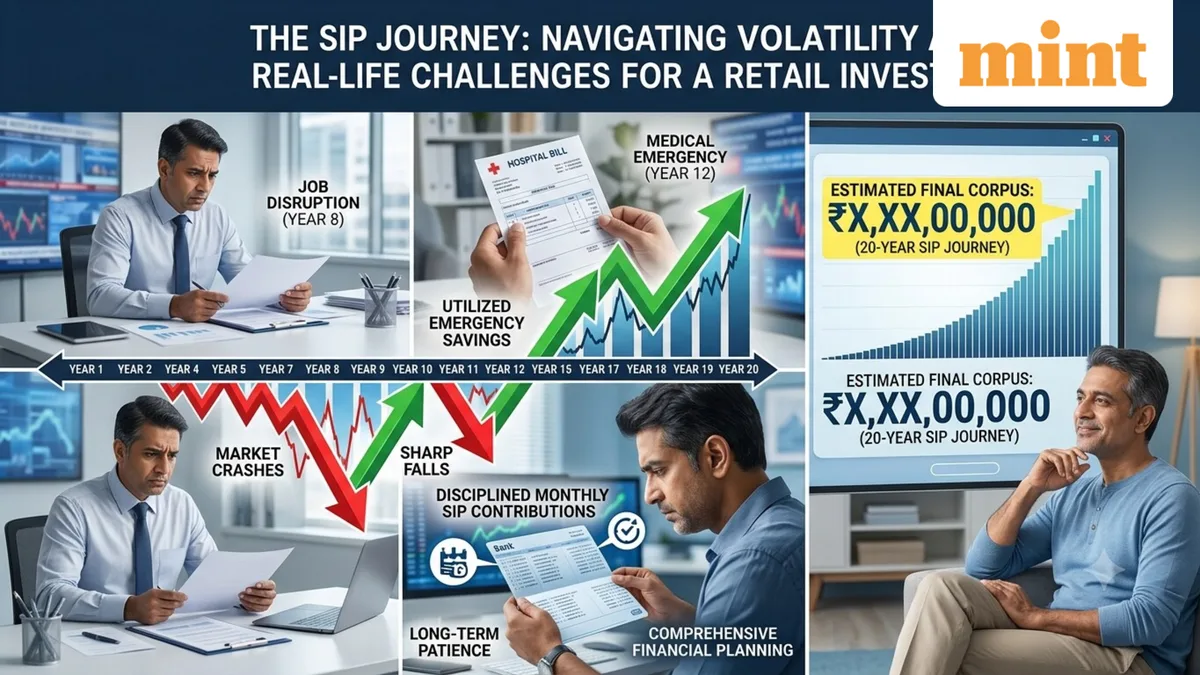
The most attractive part of a SIP is usually the wealth creation—the large corpus you could have accumulated after 10, 15, or 20 years. But that number can hide the realities investors face along the way: rising expenses, income disruptions, market crashes, and periods when returns remain disappointing.
DSP Mutual Fund, in a recent post on X, highlighted this gap between the attractive SIP illustration and the actual experience of an investor.
The fund house noted that SIP discussions often celebrate the destination (value goal achievement) and edit out the (investment) journey.
DSP pointed out that investing ₹ 10,000 every month in the Nifty 50 TRI from September 2006 to August 2026 would have meant investing ₹ 24 lakh over 240 instalments, which could have grown to around ₹ 87.3 lakh.
However, the fund house noted that “the 2006 investor didn’t earn the income the 2026 investor does” and highlighted affordability as a key constraint in SIP planning.
According to the data cited, ₹ 10,000 represented about 55% of average monthly per-capita Net National Income today, whereas 20 years ago it would have exceeded 350%.
If the SIP contribution had instead risen broadly in line with income, the equivalent starting SIP would have been around ₹ 1,536 a month and gradually increased to ₹ 10,000 today. DSP calculated that around ₹ 12.2 lakh would have been invested under this approach, resulting in a corpus of approximately ₹ 31.9 lakh.
For investors, the lesson is important: a SIP illustration should be affordable in the year you start it, not just attractive in a retrospective calculation.
Long-term investing assumes regular contributions, but real life does not always cooperate.
DSP highlighted that job losses, health emergencies, weak business periods and market crashes can arrive together.
During the Global Financial Crisis, for instance, market stress was accompanied by economic and employment uncertainty. The Covid-19 period similarly brought together a market fall, health concerns and income disruption.
The fund house noted that stopping SIPs around the GFC period could have reduced the eventual corpus from ₹ 87.3 lakh to roughly ₹ 77 lakh.
Withdrawals can have an even larger impact. DSP highlighted that a 50% withdrawal around major market events could have brought the eventual corpus down sharply—to around ₹ 75.7 lakh during the GFC trough, ₹ 61.8 lakh during the Taper Tantrum, and about ₹ 49 lakh during COVID.
This is why emergency funds, adequate insurance, liquidity, and manageable leverage matter to an SIP investor. They can help prevent long-term investments from being disrupted when short-term financial needs arise.
5News aggregated this summary from the outlet’s public feed. The full article, with all the context, is on www.livemint.com — the content belongs to LiveMint - Money.