Home loan nearly over? 5 things to do with the EMI you are about to save
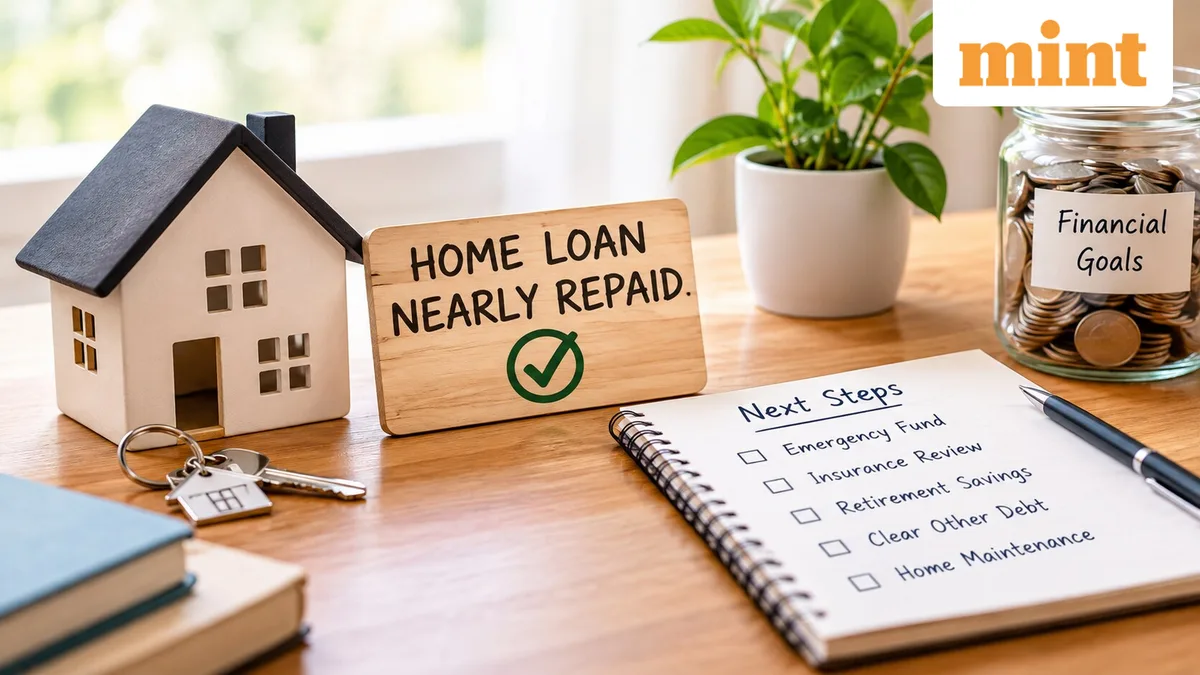
When you are left with just a few more EMIs on your ongoing home loan, it can feel like a major financial milestone. Still, when faced with such a situation, it is wise for borrowers to use this transition to their advantage and prepare for the future rather than immediately increasing discretionary spending or committing the freed-up cash flow to mutual funds or stock investments.
For example, if you have a monthly income of ₹ 50,000 and your home loan EMI is ₹ 15,000. Soon, your monthly home loan EMI is about to conclude, as you have completed the entire repayment as per the home loan terms and conditions.
Then you should spend the freed-up ₹ 15,000 recklessly or lavishly. Proper thought, time and planning must be dedicated towards making the most of the freed-up amount, so that you can meaningfully grow in life.
Keeping these basics in mind and recognising the importance of proper financial planning to achieve other financial goals seamlessly, here are several financial moves to consider once the home loan is fully repaid.
Before redirecting your EMI savings towards growth-based investments such as stocks and mutual funds, it is prudent to ensure you have an adequately healthy emergency fund.
As a norm, the fund should cover about six months of your essential expenses. This includes household costs , school fees, insurance premiums, day-to-day expenses and other unavoidable payments. This amount can also be higher for borrowers with dependents, variable income or limited job security. An emergency fund should be kept in a relatively liquid, easily available and low-risk investment option so that it is accessible when required.
The end of a home loan is also an appropriate time to reassess and analyse insurance coverage. Borrowers should check whether their term insurance is sufficient to support their family if they are no longer around. They should also review their health insurance, especially if medical costs or family responsibilities have increased since taking out the home loan.
If the home loan included loan-protection insurance, borrowers should confirm whether the policy continues after the loan is closed and understand its terms. The idea should be to conduct a thorough review of core finances and ensure stability and long-term peace of mind.
Once the EMI stops, the same amount can be redirected towards long-term financial goals. Such a step will ensure that an individual can build a more robust and comprehensive retirement corpus.
Borrowers may consider increasing contributions to retirement-oriented options such as EPF, voluntary provident fund, PPF, NPS or suitable stocks or mutual fund investments, depending on their risk profile and investment horizon . Automating this transfer can help ensure that the money is invested regularly rather than absorbed into lifestyle expenses.
Becoming debt-free from a home loan does not necessarily mean that all debt has been cleared. Borrowers should review outstanding credit card balances, personal loans, vehicle loans and other liabilities. If expensive debt remains, using the freed-up cash flow to repay it may be more beneficial than immediately increasing investments.
5News aggregated this summary from the outlet’s public feed. The full article, with all the context, is on www.livemint.com — the content belongs to LiveMint - Money.