Mortgage rates are nearing 7%, delivering another blow to a housing market already losing buyers and facing stalled sales
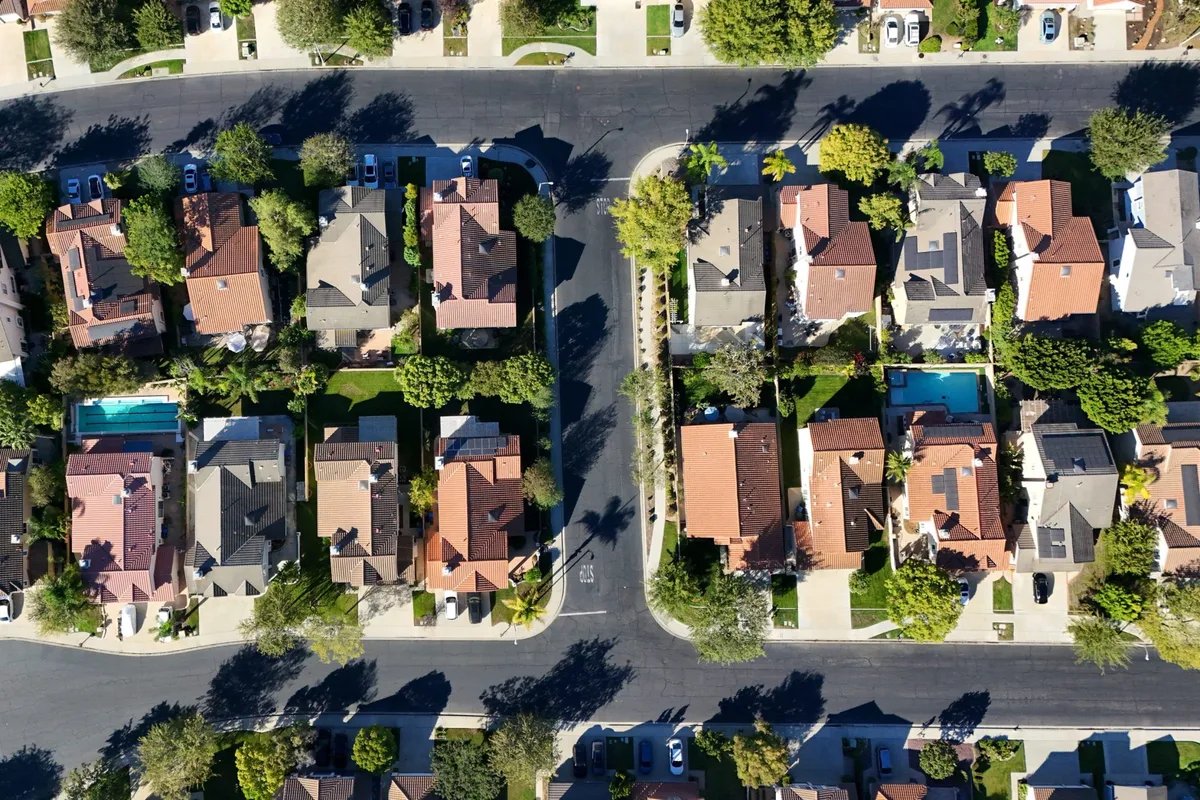
The daily 30-year fixed mortgage rate soared to 7.24% last week, adding yet another cost for homebuyers already facing the double whammy of high housing prices and inflation squeezing their wallets.
Freddie Mac’ s weekly average rate also climbed to 6.95%, putting borrowing costs at their highest level since January 2025.
The increase comes as the Federal Reserve raised interest rates to combat persistent inflation, adding pressure on borrowing costs across the economy.
The mortgage increase means some families will end up paying hundreds of dollars more per month for a house, according to Brett Johnson, a Colorado-based real estate agent.
“For some buyers, that is enough to push the house they wanted out of their budget,” he told Fortune .
Buyers are hesitating Americans were already pulling back from the housing market before the latest mortgage rate climb.
Applications for mortgages to purchase a home fell 19% from a year earlier in the week ending on Sept.
11, according to the Mortgage Bankers Association.
Even Google searches for “homes for sale” were down 15% from last year, according to real estate brokerage firm Redfin.
Fewer of the buyers who are still looking are committing to a purchase.
The number of homes that buyers agreed to buy fell to its lowest level in nearly three years during the four weeks ending Sept.
13, a 5.4% decrease from the year prior, according to Redfin.
Completed home sales are slowing too.
Sales of previously owned homes fell 2% in August, the second month in a row they declined, with the yearly sales pace falling below 4 million for the first time since June 2025, according to a National Association of Realtors report.
5News aggregated this summary from the outlet’s public feed. The full article, with all the context, is on fortune.com — the content belongs to Fortune.