₹34.8 lakh cash balance taxed as unexplained money, ITAT deletes addition and explains why declared income matters
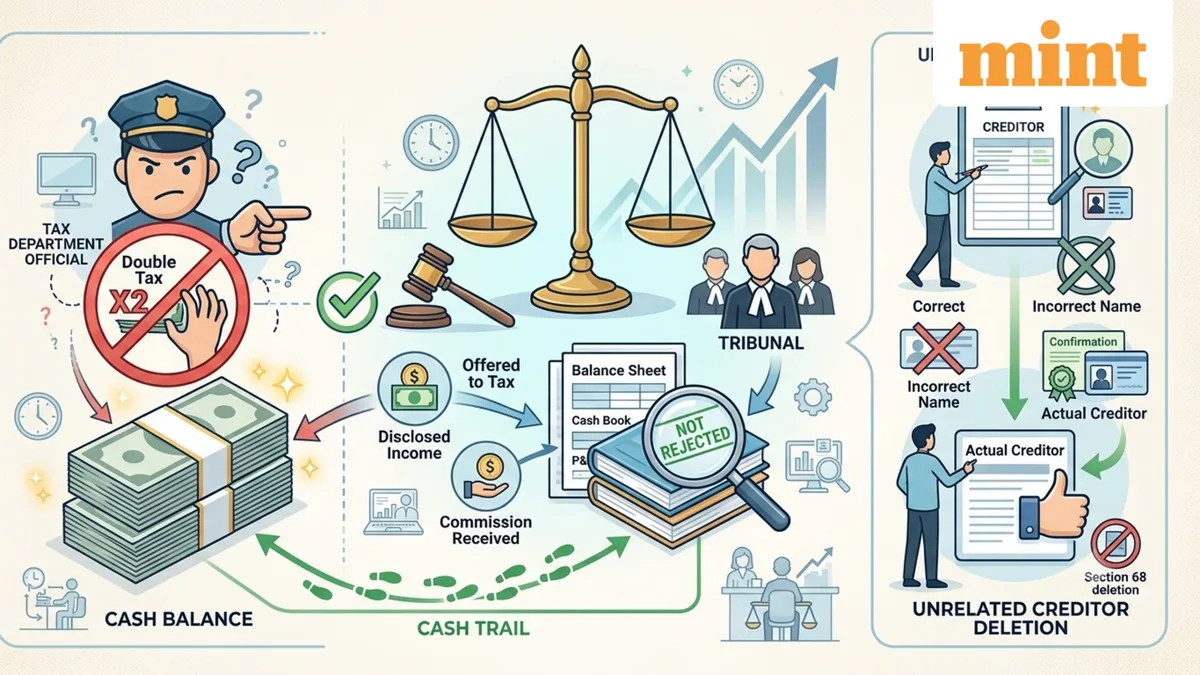
A taxpayer’s large cash balance can attract scrutiny from the income-tax department, but a closing cash balance cannot automatically be treated as unexplained money when the underlying income has already been disclosed and the books support the cash trail.
In Ankish Madhan vs ITO, Ward 29(1), Delhi, the Delhi ITAT, comprising Accountant Member M. Balaganesh and Judicial Member Sudhir Kumar, passed its order on 9 September 2026 for assessment year 2016-17 and deleted a ₹ 34.8 lakh addition made under Section 68 of the Income-tax Act.
Madhan had reported ₹ 34.8 lakh as cash in hand as of 31 March 2016. During the year, he had earned ₹ 44 lakh in commission income, including around ₹ 35 lakh received in cash . The commission income had been recorded in the books and offered to tax.
The taxpayer also produced his cash book before the assessing officer. According to the ITAT order, the cash book did not show any negative cash balance during the year. The taxpayer also furnished details of the parties from whom the commission had been received.
Despite this, the assessing officer treated the closing cash balance of ₹ 34.8 lakh as unexplained money under Section 68. The addition was subsequently upheld by the first appellate authority.
The tribunal disagreed with the tax authorities and noted that the ₹ 44 lakh commission income had already been credited to the profit and loss account and offered to tax.
The tribunal also noted that the taxpayer had maintained a cash book and that the assessing officer had not rejected the books of account. Since the cash balance could be traced to income already recorded in the books, the tribunal found no justification for treating the ₹ 34.8 lakh closing balance as unexplained separately.
The ruling does not mean that cash balances are automatically accepted by the tax department. A taxpayer still needs to establish the source of the cash and maintain supporting records.
The significance of the ruling is that where cash receipts have already been recorded as income and offered to tax, and the books provide a consistent trail to the closing cash balance, the same amount cannot simply be treated as unexplained money again merely because it remains in cash at the end of the financial year.
For taxpayers who receive cash as part of their business or professional income, maintaining a contemporaneous cash book and supporting documents can therefore become important if the cash balance is questioned during assessment.
The same appeal involved a separate ₹ 30 lakh addition under Section 68. The taxpayer had initially shown the creditor under an incorrect name but subsequently produced documents including confirmation, PAN details, income-tax records and bank statements.
The tribunal found that the evidence established the identity and creditworthiness of the actual creditor and that the transaction was supported through banking channels. It therefore deleted this addition as well.
Kirti Jha is a Senior Content Producer at Mint, where she writes on mutual funds, taxation, personal finance and macroeconomic developments.
5News aggregated this summary from the outlet’s public feed. The full article, with all the context, is on www.livemint.com — the content belongs to LiveMint - Money.