Same mutual fund category, different capital gains tax? How a scheme's portfolio can change your tax bill
If you are investing in a particular mutual fund , do not assume that all schemes in the same category will be taxed the same way when you redeem. Capital gains tax depends on the fund’s actual portfolio and how it meets the tax law’s thresholds.
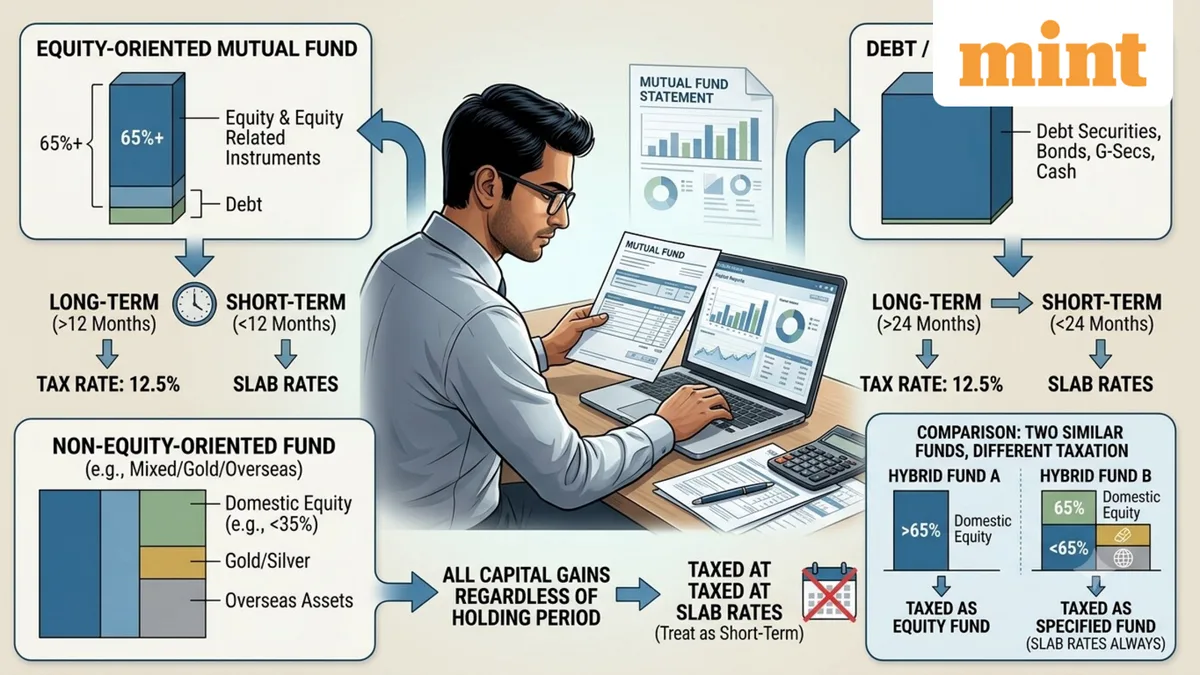
Sougata Basu, Founder and CEO, CashRich, explained that mutual funds fall into three broad groups for tax purposes. The Income Tax Act does not tax by SEBI's category name. It applies its own tests to what the fund actually holds.
Basu said, “A multi-asset fund with at least 65% in listed Indian shares qualifies as equity-oriented for taxation. If it fails this test but does not qualify as a specified mutual fund, it falls into the third group. Gains after 24 months are taxed at 12.5%, while STCG is taxed at slab rates”.
So, the asset allocation matters because it determines which tax bucket the scheme falls into. It is not enough to look only at the name of the fund, said Rohan Goyal, Investment Research Analyst, MIRA Money.
Harsh Vardhan Dawar, ACA, CFA, FRM, Founder - Wealth Cafe, highlighted these categories:
Basu said other categories also need checking. Equity savings funds have a 65% SEBI equity floor, but the tax test counts only listed Indian shares. Flexi-cap funds face a similar distinction between SEBI’s definition and the narrower tax test, particularly where overseas investments are significant.
Life-cycle funds can change tax buckets as their equity allocation reduces with maturity. Also, gold and silver funds can carry a 12-month threshold through an ETF and a 24-month threshold through an FoF, he added.
Basu explained that the fund’s actual investments, rather than its mandate alone, determine its tax classification. For equity-oriented status, at least 65% must be invested in shares of Indian companies listed on a recognised stock exchange. The test uses the annual average of monthly averages of opening and closing figures.
For specified mutual funds, the debt and money-market exposure must exceed 65%, measured using the annual average of daily closing figures. Foreign stocks, gold, silver, REITs and InvITs do not count towards the equity test. Units of other funds qualify only through a specific FoF route involving prescribed 90% thresholds, he added.
“For investors, tax classification is governed by the annual average of monthly averages of portfolio allocation,” Dawar noted.
“Tax is triggered when the investor transfers or redeems the units. A change in the fund's underlying allocation, by itself, does not mean the investor has realised a capital gain,” Goyal noted.
Basu explained that the Income-tax Act does not specify how to split a gain when a mutual fund moves from one tax classification to another during the holding period. There is no provision to tax part of the gain as equity and the remainder as non-equity.
In his view, the better interpretation is that the fund’s tax classification at the time of redemption would apply to the entire gain.
5News aggregated this summary from the outlet’s public feed. The full article, with all the context, is on www.livemint.com — the content belongs to LiveMint - Money.