NPS Vatsalya: Rules for withdrawal and exit from scheme, explained
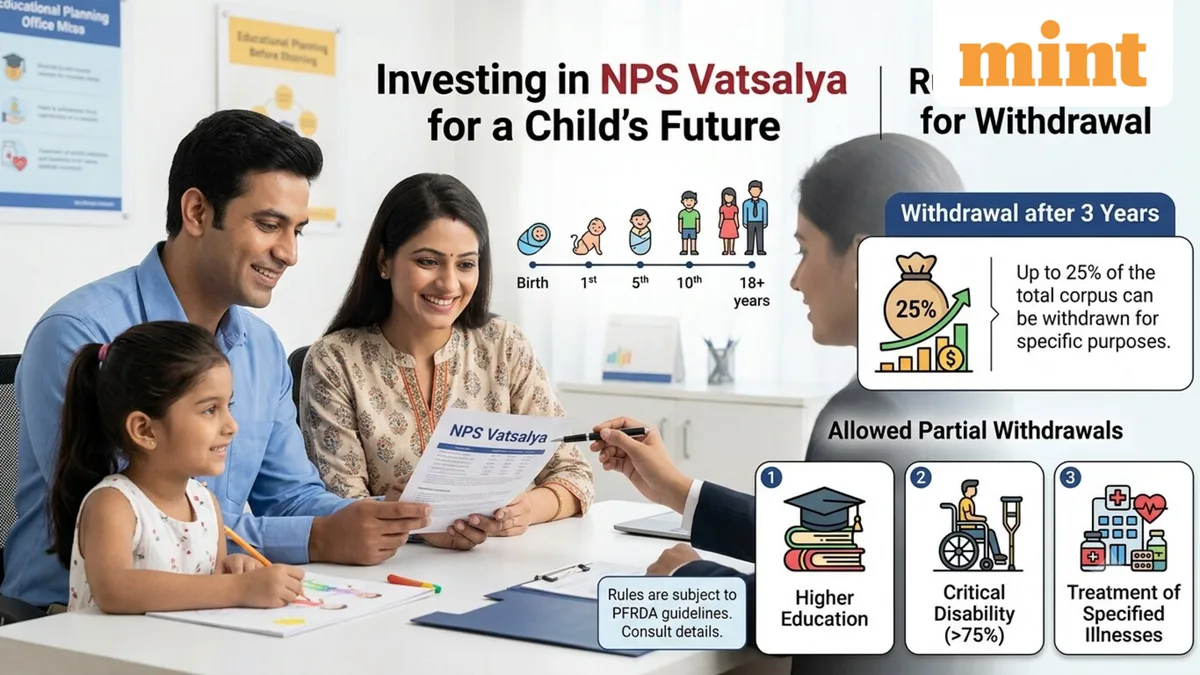
NPS Vatsalya, the National Pension Scheme's spin-off for children, allows parents to open and operate a pension account for their minor child till they attain majority age. Notably, the child retains sole beneficiary status, and the account can be easily converted to a standard NPS account after they reach 18 years of age.
Further, all tax benefits application to NPS accounts and contributions also apply to the NPS Vatsalya accounts as well.
You will be required to submit the following documents to open an account: Birth certificate of the minor, school leaving certificate/ matriculations issued by higher secondary board of respective states, passport of minor and PAN card.
Regulated and administered by the Pension Fund Regulatory Authority of India (PFRDA), the NPS Vatsalya is exclusively for minors. Launched in September 2024, it gives interest rate between 9.5% to 10%.
As per rules of eligibility, the beneficiary must be an Indian citizen, non-resident Indian (NRI) or Overseas Citizen of India (OCI) below 18 years of age. The parent or guardian operating the account on behalf of the minor will be the nominee.
NPS Vatsalya requires minimum annual contribution of ₹ 1,000. The maximum is not capped, but tax benefits are for combined ₹ 2 lakh for the parent or guardian, which includes ₹ 1.5 lakh under Section 80CCD(1B) of the Income Tax Act and ₹ 50,000 as additional deduction.
Parents or guardians can choose to invest their child's corpus under one of the following investment choices:
Notably, while it is not mandatory for the minor to have a bank account or for the parent / guardian to have a joint bank account with the minor before opening the NPS Vatsalya account; the beneficiary will be required to have a sole / joint bank account at the time of partial withdrawal or exit before the age of 18.
Here's a look at the rules for withdrawal, partial withdrawal and exit from the scheme:
Parents and guardians can also conduct partial withdrawals for education, disability (over 75%), health treatment for specified illnesses.
To initiate a partial withdrawal, you can submit a request digitally through your Central Recordkeeping Agency (CRA) portal.
Upon exit, at least 80% of the accumulated corpus must be used to purchase an annuity. The remaining balance is provided as a lump sum.
However, if the accumulated corpus is ₹ 2.5 lakh or less or if annuity purchase is unavailable from empaneled Annuity Service Providers (ASPs), subscribers can withdraw the entire amount.
Further, in case of death of parent or guardian the other responsible party should be registered with fresh KYC. And, in case of death of both parents a legal guardian can continue the scheme without contributions till child attains majority.
5News aggregated this summary from the outlet’s public feed. The full article, with all the context, is on www.livemint.com — the content belongs to LiveMint - Money.