Got a stipend while studying? ₹18.34 lakh ITAT case explains when students can claim income-tax exemption
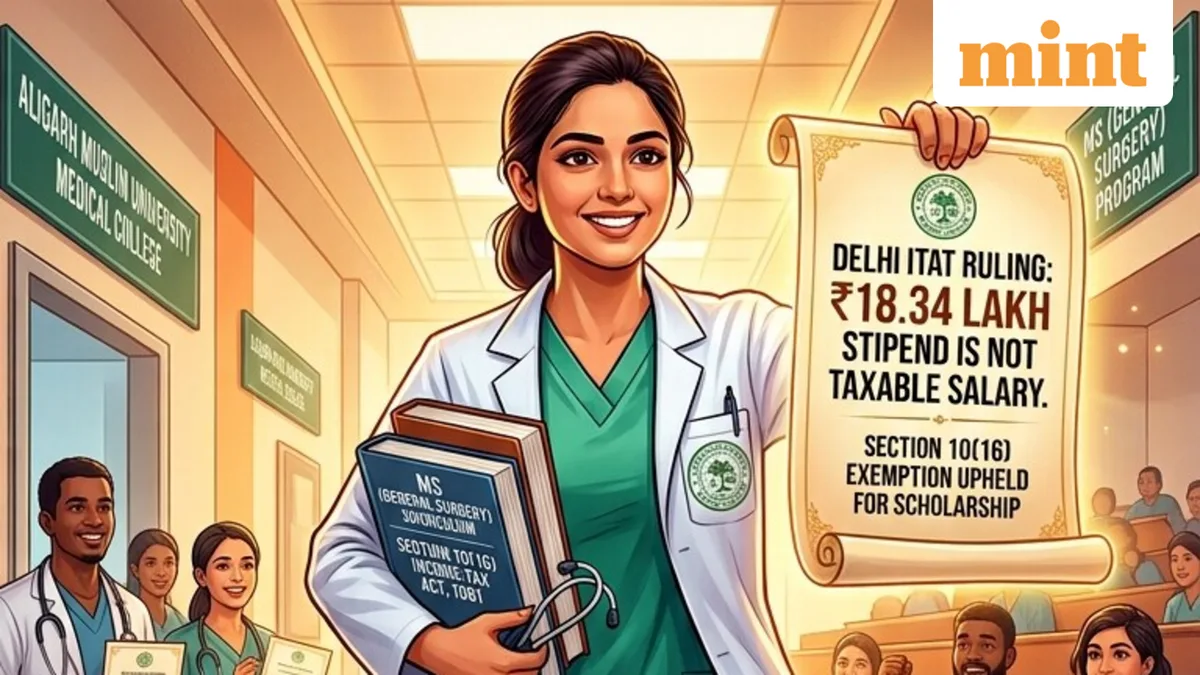
A postgraduate medical student received ₹ 18.34 lakh as stipend from Aligarh Muslim University while pursuing an MS in General Surgery. The Income Tax Department treated the amount as taxable salary, but the Delhi Income Tax Appellate Tribunal (ITAT) has deleted the addition, holding that the stipend was connected with her postgraduate education and compulsory residency training.
The ruling is important for students receiving stipends during higher education because the fact that a payment is called a stipend does not by itself determine its tax treatment. What matters is whether it is a scholarship granted to meet the cost of education, as covered by Section 10(16) of the Income-tax Act, 1961.
The ruling came in Snehlata, Rewari vs ITO, Ward-1, Sonipat, ITA No. 5462/Del/2026, for assessment year 2024-25. The order was pronounced on 30 July 2026 by the Delhi ITAT.
The case concerns Snehlata, a resident of Rewari, Haryana, who was pursuing a full-time MS (General Surgery) course during the relevant financial year. She received ₹ 18,34,578 from Aligarh Muslim University as stipend during her postgraduate medical education and compulsory residency training.
Snehlata claimed exemption under Section 10(16), treating the amount as an educational scholarship or stipend.
The Assessing Officer did not accept this treatment and treated the entire ₹ 18,34,578 as taxable salary. The first appellate authority, the Commissioner of Income Tax (Appeals)/National Faceless Appeal Centre, also upheld the addition.
Snehlata then approached the Delhi ITAT. The appeal was heard by judicial member Satbeer Singh Godara, with the order pronounced on 30 July 2026.
The Delhi tribunal examined an earlier decision of the Chandigarh ITAT in Hiteshi Aggarwal v. PCIT.
In that case, a medical doctor pursuing postgraduate studies had received ₹ 8.61 lakh as stipend. The Chandigarh ITAT had accepted the claim for exemption under Section 10(16), holding that the stipend received during postgraduate studies could not simply be equated with salary .
The Delhi ITAT found the facts in Snehlata's case to be similar. It noted that there was no dispute that she was a qualified MBBS doctor pursuing a full-time MS (General Surgery). The tribunal also recorded that the ₹ 18.34 lakh was received from Aligarh Muslim University for pursuing postgraduate medical education and the compulsory residency training attached to the academic programme.
The tribunal therefore adopted the reasoning of the earlier Chandigarh Bench decision and deleted the ₹ 18,34,578 addition.
Section 10(16) provides an exemption for scholarships granted to meet the cost of education.
The Snehlata ruling does not mean that every stipend received by a student is automatically exempt from tax. The nature of the payment and the purpose for which it is given remain important.
In the Delhi ITAT's reasoning, the relevant circumstances were that the recipient was a postgraduate medical student and the stipend was connected with her academic programme and compulsory residency training. The tribunal therefore treated the payment as a scholarship or educational stipend rather than taxable salary.
5News aggregated this summary from the outlet’s public feed. The full article, with all the context, is on www.livemint.com — the content belongs to LiveMint - Money.