Credit card utilisation: Does the 30% rule apply to each card or all cards combined?
Credit utilisation rate refers to the percentage of your available credit limit that you are using at a given time. It is calculated by dividing your outstanding credit card balance by your total available credit limit.
For example, using ₹ 50,000 against a ₹ 1 lakh credit card limit means 50% utilisation. A lower rate indicates more available credit, while a very high usage level can signal repayment pressure, even if you usually pay on time.
However, if you have multiple credit cards , the question is whether the 30% threshold should be maintained separately for each card or calculated based on your combined credit limits and outstanding balances.
No, the 30% benchmark applies to your overall credit utilisation across all cards you own. However, lenders also generally consider how much of each individual card’s limit you are using when assessing your credit profile.
So, maintaining a healthy utilisation rate is not just keeping your overall usage below 30% but it is also about avoiding very high utilisation on any single card, according to a blog post by IDFC First Bank .
A common mistake is assuming that only the combined limit matters. In reality, having one credit card with very high usage can still put pressure on your credit profile and impact future borrowings.
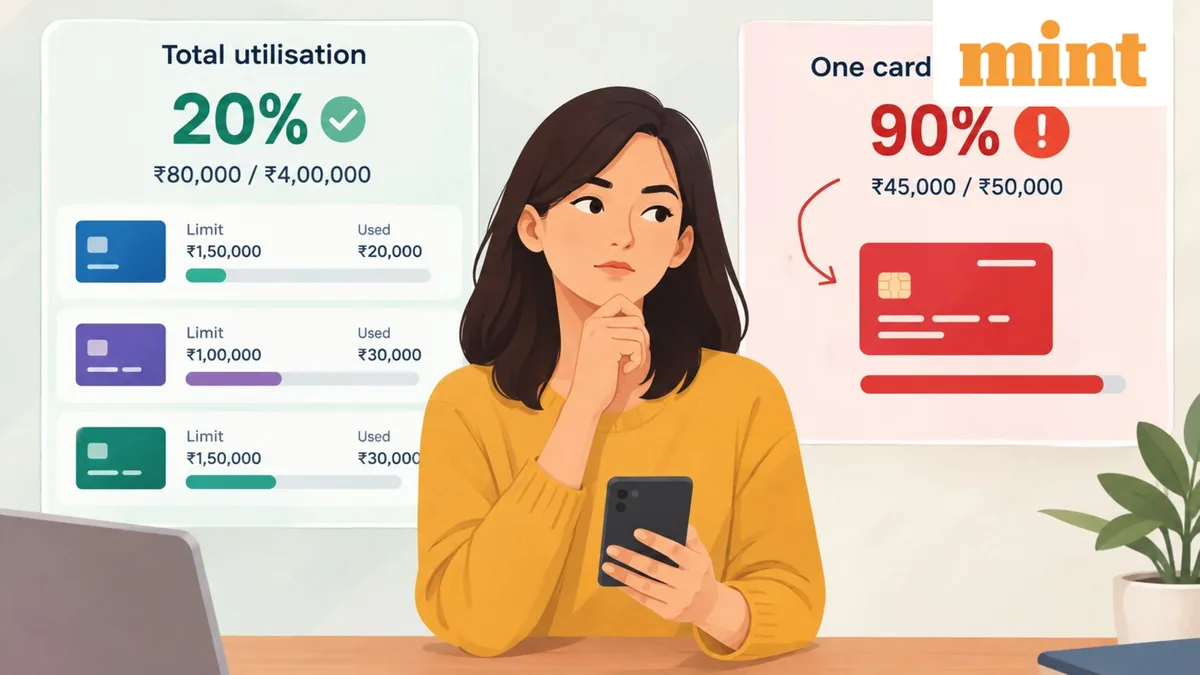
For illustration purposes, let's say a person has three credit cards with a combined limit of ₹ 4 lakh and a total outstanding balance is ₹ 80,000, giving them an overall utilisation of just 20% in that period. However, if ₹ 60,000 of that balance is on a card with a ₹ 75,000 limit, that individual card has a utilisation rate of 80%, despite the overall ratio remaining low.
“That is why relying only on the combined number can give a false sense of safety. A balanced pattern across cards usually reflects stronger credit behaviour,” the blog post read. In other words, even if overall utilisation is low, high usage on one card could still indicate greater dependence on that particular credit line.
There is also a misconception that making payments before the due date can help. This is because carrying a very high outstanding balance for a full month is not considered a healthy financial practice, even if the payment is made on time.
“Breaching 30% credit utilization, even once, can dent your credit score , as bureaus capture a snapshot of your outstanding balance on the reporting date, not your repayment history for that month. Using 90% signals financial stress to lenders, regardless of intent. The ideal utilization is below 30%, ideally under 10% for an excellent score. If a high-spend month is unavoidable, pay down the balance before your statement date to limit the bureau's visibility of peak utilization," Raj P Narayanam, Executive Chairman at Zaggle told Livemint earlier.
An individual can continue to use multiple credit cards as long as they maintain a pattern that keeps all the balances from piling up too heavily in one place, according to the bank's blog post.
It also noted a few practical habits can make a real difference, which includes:
Eshita Gain is a digital journalist at Mint, where she joined in May 2025.
5News aggregated this summary from the outlet’s public feed. The full article, with all the context, is on www.livemint.com — the content belongs to LiveMint - Money.